
A deposit can contain valuable metals without becoming a valuable operating mine. For GRML, the interesting work is the bridge between geological potential and recoverable, financeable output. A larger headline resource or a high-case model cannot build that bridge on its own.
Reading note: Presentation refreshed October 30, 2026. Original publication: 2026-10-14 (UTC). Figures, targets and company claims retain their original evidence dates; this is not a new verification or a live-price update.
Key takeaways
- Samples are research inputs. Collected bulk material is not saleable mine output.
- Resources are not reserves or cash. Recovery, processing and compliant technical evidence remain essential.
- A modeled NPV is not equity value. Ownership, taxes, capital needs and timing cannot be skipped.
- Keep projects separate. Skaergaard and Sarfartoq have different materials, development requirements and demand drivers.
Research note prepared for October 14, 2026. Greenland Mines Ltd trades on Nasdaq as GRML. Its Greenland portfolio includes the Skaergaard palladium-platinum-gold project in the east and the Sarfartoq rare-earth project in the west. This is a mineral-development story, distinct from Greenland Energy's GLND oil-exploration business.
What the reviewed field update establishes
In its 2026 field-program progress release, the company reported completion of a Skaergaard bulk-sampling program with 104.8 tons of mineralized and host material collected across seven sites. The release says those amounts were weighed during helicopter loading and that final confirmed weights would follow. The material is intended for metallurgical and pilot-scale test work, rather than being saleable mine output.
Samples cover palladium-platinum-dominated, gold-dominated, and vanadium-bearing horizons. Collecting material from several sites can help test variation in ore characteristics and processing performance. It cannot by itself establish an economically recoverable reserve or a commercially viable processing plant.
The same release describes Sarfartoq's first full field season following the September 1, 2026 acquisition. Work includes structural mapping and environmental baseline studies. A field camp and baseline data are development inputs, not equivalent to an exploitation permit or a constructed mine.
Evidence supporting further research
104.8 tons
Reported Skaergaard bulk materialField-measured mineralized and host material for test work, with final weights still to be confirmed in the release.
Seven sites
Sampling coverageMore sites than initially planned can help characterize variability; representativeness and laboratory results still matter.
Two-year baseline period
Sarfartoq environmental dataThe company reports data spanning the minimum baseline period required by the relevant Greenland agency; this does not mean all permitting requirements have been met.
The constructive thesis is that better technical evidence could clarify processing routes, resource confidence, environmental design, and development options. Precious metals and rare-earth magnet materials also have different demand drivers, so each project requires its own economic assessment.
Treat assessment values carefully
The release cites a Sarfartoq Initial Assessment high-case pre-tax net present value of approximately $2.05 billion and a pre-tax internal rate of return of 118.6%. These are modeled project results under specified assumptions and include Indicated and Inferred Mineral Resources. They are not GRML's market capitalization, realized profit, cash balance, or a forecast return available to someone buying the stock.
A high-case, pre-tax project NPV cannot be compared directly with the listed company's equity value without examining capital spending, taxes, financing, ownership, timing, commodity assumptions, recovery rates, and execution risk. Inferred resources carry greater geological uncertainty than higher-confidence categories. Historical non-S-K 1300-compliant assays described in the release should not be substituted for the current compliant estimate.
Risks that deserve equal weight
- Metallurgy: valuable metals in rock do not guarantee acceptable recovery, concentrate quality, or saleability.
- Capital intensity: mine, processing, power, transport, and environmental facilities may require substantial financing.
- Permitting and local engagement: baseline work is only part of the approval process.
- Commodity exposure: palladium, platinum, gold, vanadium, and rare-earth prices can alter project economics differently.
- Remote logistics: Greenland's operating conditions can affect construction schedules and costs.
- Dilution and corporate obligations: project progress must be assessed alongside share count, warrants, cash burn, and the full corporate balance sheet.
- Model sensitivity: optimistic technical or price assumptions can overstate the margin of safety.
Next evidence to watch
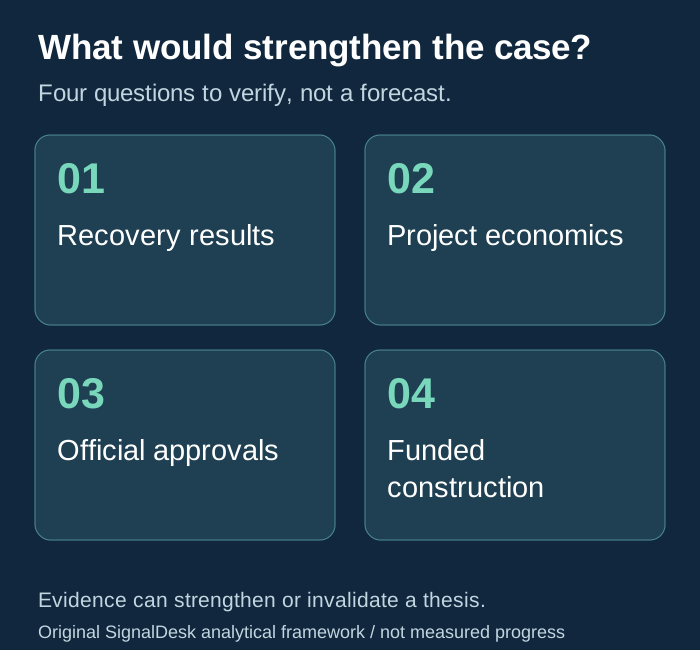
Follow independently prepared metallurgical results, revised compliant technical reports, project-by-project capital and operating costs, financing terms, and official permitting milestones. For any modeled valuation, read the base case and downside sensitivities as well as the highlighted high case. A completed study should make the remaining uncertainties clearer, not merely produce a larger headline number.
Bottom line
GRML is an early-stage mineral-development watchlist candidate. The useful signal is the generation of better technical evidence, not a claim that a mineral inventory or modeled NPV belongs to shareholders as immediately realizable value. Recovery, financing, approvals, construction, and dilution determine whether the geological opportunity becomes durable per-share value.
Sources and evidence date
Evidence reviewed October 14, 2026. This is a research assessment, not a claim that the cited field update was released today. Company field-program announcement reproduced by MarketScreener: https://www.marketscreener.com/news/greenland-mines-provides-progress-update-on-2026-field-programs-at-skaergaard-and-sarfartoq-ce785bdcdc8bff27
Official company site and technical presentation links: https://greenlandmines.com/
Use the company's current SEC filings and technical reports to check subsequent developments: https://www.sec.gov/edgar/search/
The small/micro-cap label follows the portal's delayed October 14 snapshot. Extreme-volatility and speculative-risk labels are editorial cautions, not measured forecasts. No current production, approved mine, or guaranteed economic return is asserted. Educational commentary only; not personalized investment advice.
Connect the research
The similarly named oil explorer is a different business; compare Greenland Energy (GLND): Permits and the First Well Before the Oil Story. It retains its own research and reporting dates.
For another example of why an operating activity and a mineral-development project need separate analysis, read ABAT Stock: Recycling Growth Meets Margin and Funding Risks. It retains its own research and reporting dates.
What would change your view?
Would recovery results, a less optimistic economic case or funded construction change your GRML view most? Add your reasoning and a dated source in the article discussion below, or continue in the $GRML Stock Room. Challenge the evidence and assumptions, not other readers.
Presentation-only refresh: original sources, dated figures, forecast caveats and disclosure statements are retained. The new illustrations explain the analytical questions; they are not current-price charts or forecasts.